Small Business Finance :: News
SHARE

Share this news item!

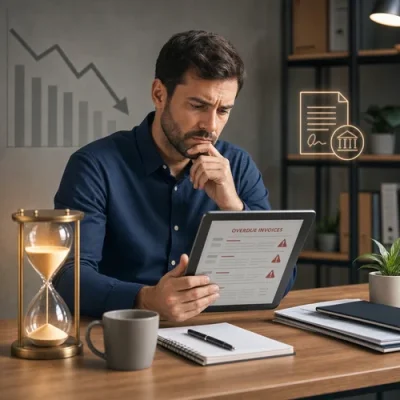
Why Unpaid Invoices Still Shape Small Business Borrowing

Debtor discipline is becoming a finance strategy, not just admin

Why Unpaid Invoices Still Shape Small Business Borrowing?w=400

The information on this website is general in nature and does not take into account your objectives, financial situation, or needs. Consider seeking personal advice from a licensed adviser before acting on any information.

Fresh small business payment data has put a familiar pressure point back on the agenda for Australian SMEs: invoices are still taking too long to turn into cash.
While many operators are seeing pockets of stronger demand, that does not always translate into immediate liquidity.
For businesses with wages, rent, suppliers and tax instalments due on fixed dates, even a short delay in customer payments can create a funding gap.

The issue matters because late payments do more than inconvenience the accounts team. They can change the way a business uses debt. A profitable business may still need short-term finance if money is tied up in receivables. Conversely, a business that tightens invoicing, follows up debtors earlier and sets clearer payment terms may reduce the amount it needs to borrow, or improve its position when applying for finance.

For lenders, debtor quality is increasingly part of the broader risk picture. Bank statements, aged receivables, BAS history and cash flow patterns can all help show whether a business has predictable income or is constantly plugging gaps. SMEs that can demonstrate disciplined collections, stable margins and realistic forecasts are generally better placed to discuss loan purpose, repayment capacity and suitable structures.

This is where finance planning becomes practical. If delayed invoices are seasonal or linked to a few large customers, a revolving line of credit, invoice finance or other working capital finance options may be more appropriate than a long-term loan. If the need is tied to expansion, equipment or hiring, owners should separate growth funding from cash flow support so the loan term matches the business purpose.

SMEs should also avoid treating available credit as a substitute for debtor management. Before taking on new funding, it is worth reviewing payment terms, automating reminders, checking customer concentration risk and stress-testing what happens if major invoices arrive one or two weeks late. Business owners can also model repayments under different rate and term scenarios to see whether a proposed facility remains affordable if revenue timing slips.

The key lesson is not that borrowing is a problem. Used carefully, finance can smooth timing gaps and support growth. But late payments can quietly turn a manageable facility into an expensive habit. For Australian SMEs, stronger debtor discipline and clearer funding strategy now go hand in hand.

Published:Tuesday, 25th Aug 2026
Author: Paige Estritori

Please Note: We do not endorse any specific products or companies. Some content is sourced from third parties, including press releases, and may not be independently verified for accuracy or completeness.

Share this news item:

Rate this article

0 Comments

No comments yet. Be the first to share your thoughts.

Finance News

Why Rising Debt Stress Should Prompt SMEs to Review Finance Early
15 Sep 2026: Paige Estritori
Fresh industry attention on small business debt stress is a timely reminder that borrowing pressure rarely appears overnight. For many Australian SMEs, the squeeze builds gradually: a slower sales month, higher supplier costs, delayed customer payments, tax instalments, payroll commitments and existing loan repayments all competing for the same working capital. - read more
What the Instant Asset Write-Off Means for SME Borrowing
08 Sep 2026: Paige Estritori
Australian small businesses are again watching the instant asset write-off closely, with the federal government seeking to keep the threshold available for eligible assets. For many SMEs, the measure can make planned investment in tools, vehicles, technology or machinery more attractive because the cost of qualifying assets may be deducted sooner rather than depreciated over several years. - read more


Business Loans Articles

Loan Refinancing Explained: A Comprehensive Guide for Australian Entrepreneurs
Cash flow is the lifeblood of any business, particularly for startups. It refers to the amount of cash that comes in and goes out of a business. Proper management of this flow is crucial for the success and sustainability of new enterprises. Ensuring a positive cash flow allows businesses to meet their financial obligations, invest in growth opportunities, and manage unexpected expenses. - read more
Cash flow tips for startup success in Australia
Cash flow is the money moving in and out of a business. For startups, managing it carefully can be just as important as making sales, because bills, wages, suppliers and growth expenses often need to be paid before revenue is predictable. - read more

Need Help Finding a Loan?

Business Loan Repayment Calculator

Business Loan Repayment Calculator

Small Business Finance SME Newscast

Small Business Finance SME Newscast

Stay informed with MoneyTips

Get practical financial information, news, guides and resources.

All finance quotes are provided free (via our secure server) and without obligation.
We respect your privacy.

Knowledgebase
Mortgage Document:
The physical contract agreement that a Mortgagee (lender) enters into with a Mortgagor (borrower) outlining the precice terms of a mortgage loan.