Small Business Finance Business Loan Repayment Calculator
Explore potential business finance scenarios with our Business Loan Calculator. Test different borrowing amounts, interest rate assumptions and loan structures to see how various scenarios may influence your estimated repayments and overall finance costs.
Calculator results are estimates based on the inputs and assumptions used and are provided for general information only. They are not quotes, offers, approvals, eligibility assessments or personalised recommendations. Actual costs and repayments may differ.
Business Loan Details:
Important!
Business Loan Interest Rates differ from lender to lender and will depend on your individual circumstances (credit history, employment status, age, etc.).
Business Loan Amortisation Calculator
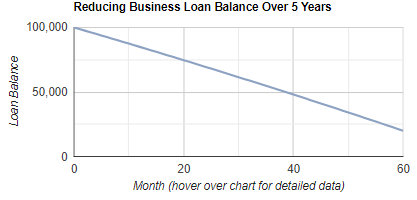
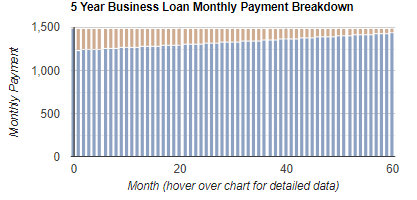
The following amortisation graphs detail month-by-month data on the progress of the proposed loan. The first chart below examines the reducing loan balance over the course of the finance contract term. The second graph illustrates the portion of each monthly repayment allocated to payment of interest vs principal reduction.
How to use our Business Loan Repayment Calculator
Our Business Loan Repayment Calculator helps you estimate business loan repayments, compare finance options and understand the true cost of borrowing before you commit. It is important because small changes to your loan amount, interest rate, term or balloon payment can materially change cash flow, total interest and end-of-term obligations. This calculator provides an indicative estimate only and is designed to support planning and budgeting for business growth.
How to complete each section for the best result:
1. Loan Amount
Enter the amount you expect to borrow as a whole number (no dots or commas). Include any costs you plan to capitalise into the loan, such as stamp duty, registration, insurance or other applicable fees, so the estimate reflects your real financed amount.
2. Balloon or Residual Payment (optional)
Select a residual as a percentage of the purchase price. A higher residual usually reduces ongoing repayments, but increases the amount due at the end and can increase total interest over the term. Choose a residual only if you have a realistic plan to refinance, pay it out, or sell an asset to meet the final amount.
3. Term of Loan
Select the number of years you want to repay the loan. A longer term generally lowers periodic repayments but increases total interest paid. A shorter term can reduce total cost but may place pressure on cash flow.
4. Interest Rate
Select an indicative annual interest rate to run a scenario. Your actual rate depends on lender assessment and your business circumstances, so consider testing multiple rates to stress-test affordability.
How to interpret the results:
1. Repayment estimate
Use the repayment figure as a budgeting guide for regular cash flow planning. If you selected a residual, remember the final payout is additional to the periodic repayments.
2. Amortisation charts
Review the reducing loan balance over time and the split between interest and principal. Early repayments typically include a higher interest component, with principal reduction accelerating later.
General information only, not personal financial advice. It does not consider your objectives, financial situation or needs. Consider the loan contract, fees, repayment frequency, and whether the repayments remain affordable under higher rates or lower revenue, and seek professional advice if required.
Australian small businesses can access several types of business finance, from term loans and lines of credit to equipment finance, invoice finance and commercial property loans. This guide explains how common business loan structures generally work and what to consider before applying. - read more
Cash flow refers to the movement of money into and out of your business. It encompasses all the income your business earns from sales, payments from customers, and investments, as well as all the expenses for operational costs, salaries, and other expenditures. - read more
ASIC’s latest private credit surveillance, released on 10 November 2026, is a timely reminder that the funding source behind a business loan can matter almost as much as the headline rate. While the regulator’s report is primarily focused on investor disclosure and fund governance, Australian SMEs watching the non-bank lending market should also note the broader message: complexity, unclear fees and weak transparency can create risks for everyone connected to a credit chain. - read more
Australian small businesses that use credit cards to manage tax payment timing have been given extra breathing room, after the federal government confirmed the ATO will continue accepting credit card payments until 30 June 2027. The reprieve follows backlash over the ATO’s earlier plan to stop direct credit card payments after 30 November 2026, a change linked to the national card surcharge reforms that began on 1 October. - read more