The information on this website is general in nature and does not take into account your objectives, financial situation, or needs. Consider seeking personal advice from a licensed adviser before acting on any information.
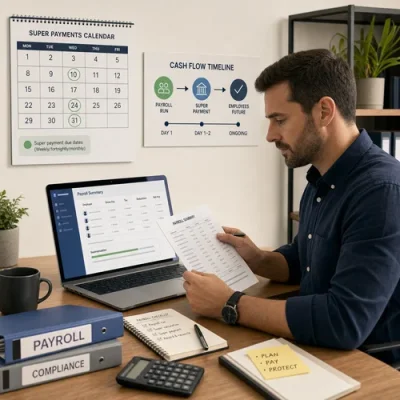
Australian small businesses are being urged to prepare for a major payroll change as payday super moves closer.
From 1 July 2026, employers are expected to pay superannuation at the same time as salary and wages, rather than relying on the current quarterly cycle.
While the policy is designed to improve retirement savings and reduce unpaid super, it also has practical cash flow implications for SMEs.
For many operators, quarterly super payments have acted as a timing buffer. That buffer can be risky if funds are not set aside properly, but it has still allowed some businesses to manage uneven income, late customer payments and seasonal trading swings. Moving to payday-based super means cash will leave the business more frequently, so payroll discipline will matter even more.
The change does not necessarily mean every business will need extra finance. Strong operators may simply adjust systems, budgets and payment routines. However, SMEs with tight margins, lumpy revenue or a history of using quarterly obligations to manage short-term pressure should start reviewing their working capital position well before the deadline.
A useful first step is to map payroll, PAYG withholding, super, rent, supplier accounts, BAS and existing loan commitments across the same forecast period. This can reveal whether a business has a genuine funding gap or simply needs better timing controls. Where debt is already in place, owners should also estimate repayments under different rate and term assumptions before adding new facilities.
Finance strategy should also reflect the purpose of the borrowing. A short-term working capital facility may suit temporary timing gaps, while a line of credit may help businesses with recurring peaks and troughs. Longer-term loans are generally better matched to assets, expansion or structural investment, not routine payroll obligations. Using the wrong facility can make a manageable compliance change more expensive than it needs to be.
Preparation may also support loan approval. Lenders typically want to see clean bank conduct, current tax and super obligations, stable revenue and a clear explanation of how funds will be used. Businesses that can show they have planned for payday super are likely to present a stronger risk profile than those seeking urgent finance after cash has already tightened.
The message for SMEs is to treat payday super as more than a payroll software update. It is a chance to strengthen cash flow habits, review funding buffers and ensure finance decisions are made early, calmly and with a clear repayment plan.
Please Note: We do not endorse any specific products or companies. Some content is sourced from third parties, including press releases, and may not be independently verified for accuracy or completeness.


Payday super will definitely expose who’s been leaning on quarterly timing, but mapping BAS and payroll together seems the sensible first move.