The information on this website is general in nature and does not take into account your objectives, financial situation, or needs. Consider seeking personal advice from a licensed adviser before acting on any information.
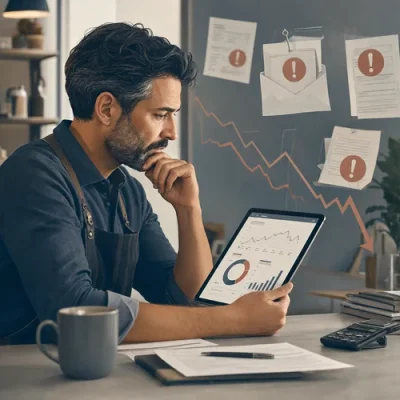
Fresh industry attention on small business debt stress is a timely reminder that borrowing pressure rarely appears overnight.
For many Australian SMEs, the squeeze builds gradually: a slower sales month, higher supplier costs, delayed customer payments, tax instalments, payroll commitments and existing loan repayments all competing for the same working capital.
The key lesson for business owners is not simply that conditions remain challenging. It is that early action can preserve choices. Once arrears deepen, lenders may take a more cautious view of the business, the Australian Taxation Office may become more active in recovery, and directors can find themselves making decisions under time pressure rather than from a position of control.
For SMEs already using business loans, overdrafts, credit cards or equipment finance, now is a sensible time to revisit repayment capacity. That means looking beyond whether this week’s bills can be paid and testing whether the business can handle a quieter trading period, a large BAS payment, or a customer taking longer than expected to pay. Practical cash flow discipline remains one of the strongest defences against finance stress.
Owners considering new finance should also be careful not to treat debt as a quick fix for a structural problem. A short-term business loan or line of credit can be useful when it bridges a timing gap, funds profitable work, or supports a clear recovery plan. It can become risky when it is used to cover ongoing losses without changes to pricing, expenses, payment terms or stock management.
Before applying or refinancing, SMEs should consider:
- whether the loan purpose is temporary, productive and clearly documented;
- how repayments fit with seasonal revenue and upcoming tax obligations;
- whether existing debts can be consolidated without extending pressure unnecessarily;
- what financial records, bank statements and forecasts a lender is likely to review;
- whether directors have allowed for interest, fees and repayment frequency, not just the headline rate.
This is where preparation can materially improve outcomes. Updating management accounts, chasing overdue invoices, negotiating supplier terms and modelling repayments under different scenarios can give owners a clearer view of affordability before they commit.
The broader message is constructive rather than alarmist. Debt can remain a useful tool for Australian small businesses, especially where finance supports growth, equipment, stock, contracts or working capital timing. But in a tighter environment, lenders want evidence that the business understands its numbers. SMEs that engage early, communicate clearly and plan around cash flow are generally better placed than those waiting until every option feels urgent.
Please Note: We do not endorse any specific products or companies. Some content is sourced from third parties, including press releases, and may not be independently verified for accuracy or completeness.


No comments yet. Be the first to share your thoughts.